

The Ultimate Guide to Engagement Ring Financing and Credit Options
Engagement Ring Financing Options: What You Need to Know Before You Buy
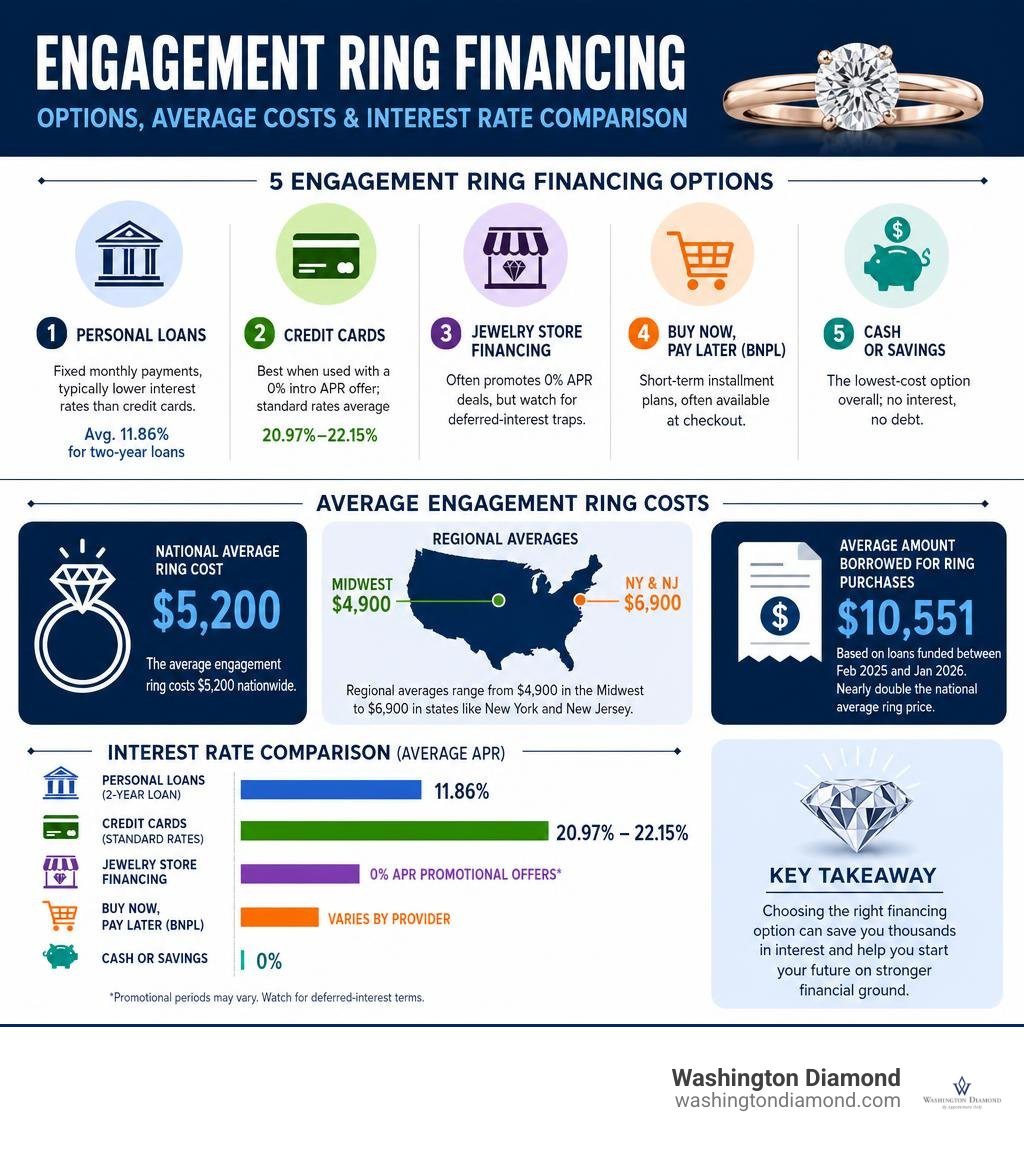
The main engagement ring financing options available to buyers in 2026 are:
- Personal loans — Fixed monthly payments, typically lower interest rates than credit cards (avg. 11.86% for two-year loans)
- Credit cards — Best when used with a 0% intro APR offer; standard rates average 20.97%–22.15%
- Jewelry store financing — Often promotes 0% APR deals, but watch for deferred-interest traps
- Buy Now, Pay Later (BNPL) — Short-term installment plans, often available at checkout
- Cash or savings — The lowest-cost option overall; no interest, no debt
The average engagement ring costs $5,200 nationwide — and buyers are often surprised by how quickly that number climbs once you factor in the diamond quality, band material, and design details. Regional averages range from $4,900 in the Midwest to $6,900 in states like New York and New Jersey. And according to data from the Credible personal loans marketplace, the average amount actually borrowed for ring purchases between February 2025 and January 2026 was $10,551 — nearly double the national average ring price.
That gap tells a real story. Many buyers are spending more than they planned, and choosing how to pay for it matters a lot — both for your wallet today and your financial health tomorrow.
I'm Tom Daube, a GIA-certified diamond expert and jewelry designer who has spent decades helping buyers find exceptional diamonds at prices well below typical retail. Navigating engagement ring financing options is something I guide clients through regularly, because the right ring at the right price — funded the right way — sets a much stronger foundation for a life together. Let's break it all down clearly so you can make a confident, informed decision.
How Much Should You Spend on an Engagement Ring?
For decades, the jewelry industry pushed the famous "two-to-three months’ salary" rule. But let’s be honest: that guideline wasn’t created by financial planners. It was a highly successful marketing campaign launched in the mid-20th century by De Beers to convince buyers to spend more.
Today, we take a much more sensible, values-based approach to budgeting. Starting a marriage with unnecessary financial stress is like building a house on quicksand. Instead of sticking to an arbitrary percentage of your income, you should look at your actual savings, your current monthly cash flow, and your upcoming life goals—such as buying a home in Northern Virginia, planning the wedding, or paying down student debt.
To give you an idea of what people are actually spending, let's look at the numbers. Nationally, the average price of an engagement ring sits at $5,200. However, location plays a massive role in these averages. In the Mid-Atlantic region (including New York, Pennsylvania, New Jersey, and Delaware), buyers spend an average of $6,900. Meanwhile, lovebirds in many Midwestern states spend a more modest average of $4,900.
At Washington Diamond, we serve clients throughout Northern Virginia who have highly diverse budgets. We believe that the value of an engagement ring lies in its symbolism and craftsmanship, not in a massive price tag that compromises your peace of mind. To help you figure out how to balance diamond size, metal choices, and design elements within your target price range, we recommend reading our Engagement Ring Prices Guide 2026.
If you want to play around with the numbers and see how different combinations of the "Four Cs" (Cut, Color, Clarity, and Carat weight) affect the final cost, you can also use The Diamond Value Calculator Your Secret Weapon for Smart Buying. This tool is designed to show you exactly where you can save money without sacrificing visual beauty.
Comparing Your Engagement Ring Financing Options
Choosing the right way to fund your purchase is just as important as choosing the diamond itself. If you do not have the full amount saved in cash, or if you prefer to keep your liquid savings intact for emergencies, you will need to evaluate the different engagement ring financing options available to you.

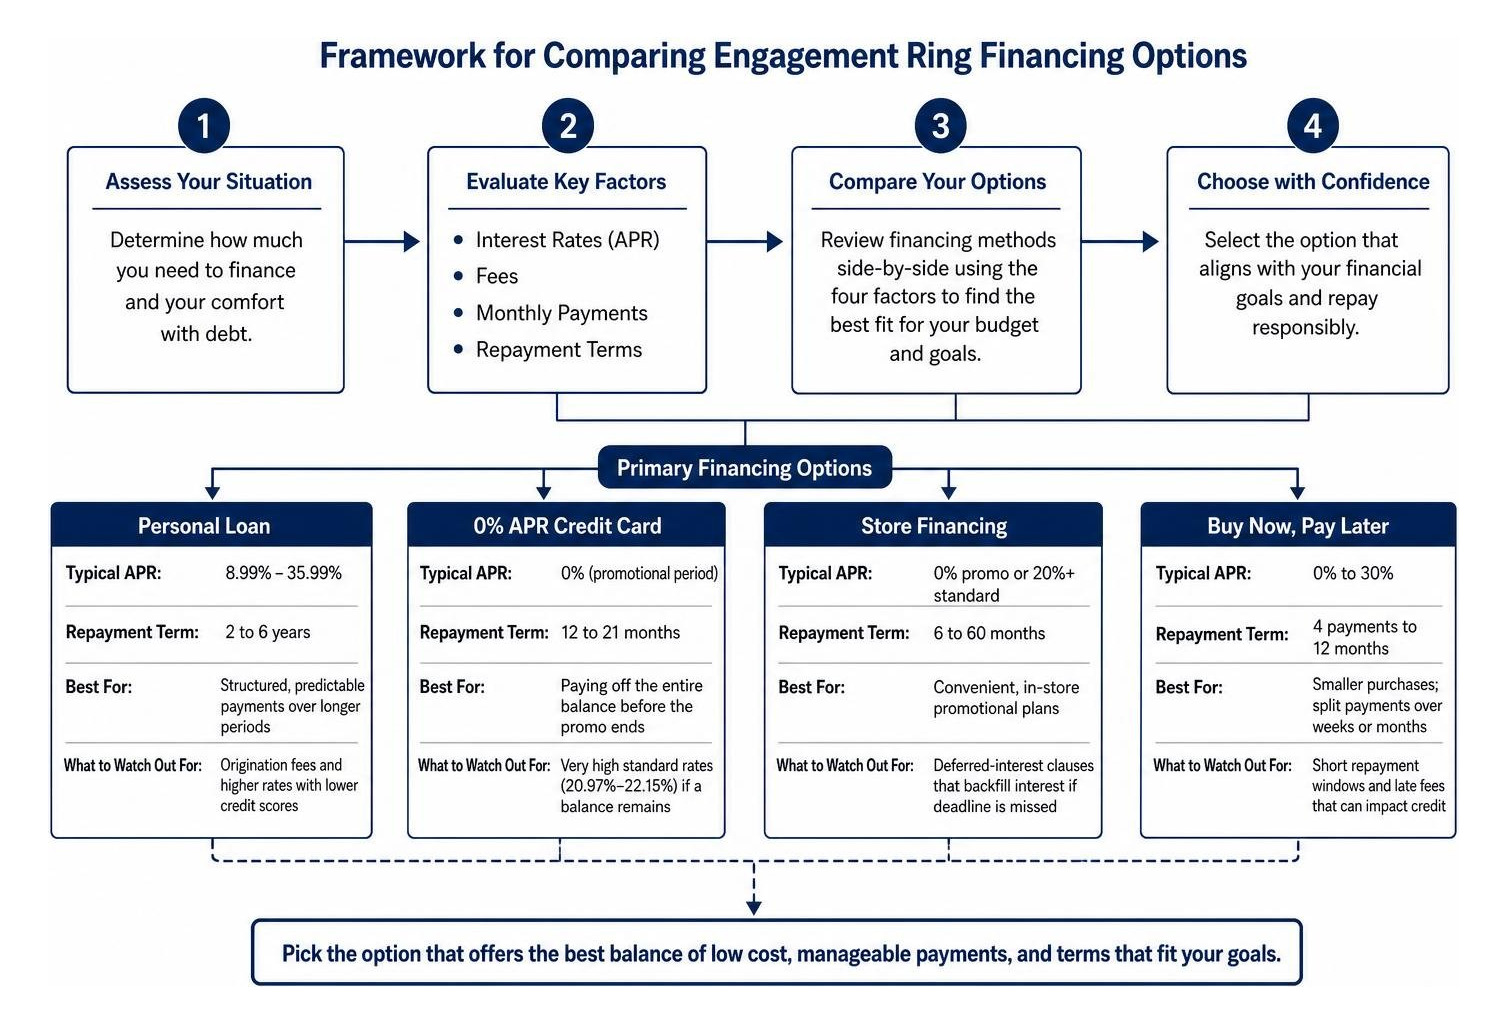
When comparing your financing choices, we recommend using a simple four-part framework:
- Interest Rates (APR): How much will borrowing this money actually cost you over time?
- Fees: Are there upfront origination fees, late fees, or prepayment penalties?
- Monthly Payments: Will the monthly payment fit comfortably into your post-proposal budget?
- Repayment Terms: How long will you be paying off this debt?
To help you visualize how these options stack up, here is a quick overview of the primary financing routes:
| Financing Method | Typical APR Range | Repayment Term | Best For | What to Watch Out For |
|---|---|---|---|---|
| Personal Loan | 8.99% – 35.99% | 2 to 6 years | Buyers who need structured, predictable monthly payments over a longer period. | Origination fees and higher interest rates if your credit score is lower. |
| 0% APR Credit Card | 0% (promotional period) | 12 to 21 months | Buyers who can comfortably pay off the entire balance before the promo period ends. | Extremely high standard interest rates (20.97%–22.15%) if a balance remains. |
| Store Financing | 0% promo or 20%+ standard | 6 to 60 months | Buyers looking for convenient, in-store promotional plans. | Deferred-interest clauses that backfill interest if you miss the payoff deadline. |
| Buy Now, Pay Later | 0% to 30% | 4 payments to 12 months | Buyers making smaller purchases who want to split up payments over a few weeks or months. | Short repayment windows and potential late fees that can impact your credit. |
To help you decide which route aligns best with your financial goals, consider this decision-making process:
Deep Dive into Popular Financing Methods
Now that we have looked at the high-level comparison, let's take a closer look at how each of these engagement ring financing options works in the real world, including the specific terms, credit requirements, and potential pitfalls you need to keep in mind.

Personal Loans as Engagement Ring Financing Options
A personal loan is an unsecured debt that you repay in fixed monthly installments over a set period, typically between two and six years. Because the interest rates are fixed, your monthly payment will never change, making it highly predictable and easy to budget for.
Interestingly, the average disbursed loan amount for engagement ring financing on the Credible personal loans marketplace from February 2025 through January 2026 was $10,551. This suggests that buyers who choose the personal loan route often use the funds to purchase higher-end custom rings or to cover additional proposal-related expenses, such as travel or professional photography.
The average interest rate on a two-year personal loan is 11.86%, which is significantly lower than the average credit card interest rate of 22.15%. However, your actual rate will depend heavily on your credit score and financial history. For example, personal loans through lenders like Prosper feature APRs ranging from 8.99% up to 35.99%, with terms of two to six years and origination fees ranging from 1% to 9.99%. To give you an idea of the real-world cost: the average APR for Prosper loans with a three-year term funded between January 1, 2026, and March 31, 2026, was 24.19%.
If you are considering this path, you can explore rates and check your eligibility by reading How To Finance Your Engagement Ring or looking into the specific lending terms on Engagement Ring Financing.
Credit Cards and Store Credit Cards
Using a credit card to finance an engagement ring can be incredibly smart—or incredibly expensive.
The smart way to do it is by opening a new credit card that offers an introductory 0% APR promotional period. Many cards offer 0% interest on purchases for 12, 15, or even 21 months. If you put the ring on this card and diligently pay off the balance before the promotional period expires, you essentially get a free loan. Plus, you can rack up significant cash-back rewards or travel points on the purchase.
The risky way is carrying a balance on a standard credit card or failing to pay off a promotional card before the deadline. With average credit card interest rates hovering between 20.97% and 22.15%, carrying a $5,000 balance can quickly add hundreds or thousands of dollars to the total cost of your ring.
Store credit cards are also notorious for "deferred interest" promotions. If a jeweler offers "0% interest for 12 months" through their store card, read the fine print carefully. In many cases, if you have even a $10 balance remaining at month 12, the lender will backfill and charge you interest on the entire purchase amount starting from day one. To learn more about maximizing your budget and avoiding high retail markups altogether, check out our guide on Affordable Bling Top Tips for Best Value Engagement Rings.
Buy Now, Pay Later (BNPL) Engagement Ring Financing Options
Buy Now, Pay Later (BNPL) services have surged in popularity over the last few years. These services allow you to split your purchase into equal installments—often four interest-free payments over six weeks, or longer-term monthly payment plans of 3 to 12 months with interest.
While BNPL can be highly convenient for online checkouts, it is generally best suited for lower-priced rings or for covering a small remaining balance. The repayment windows are typically very short, meaning your monthly or bi-weekly payments will be quite high if you are buying a premium diamond. If you are trying to weigh different design styles and see how they fit into your budget, we offer dedicated Engagement Ring Comparison Help to assist you in making the most cost-effective choice.
Smart Alternatives to Financing: Cash and Savings
While financing is a great tool when used responsibly, paying with cash or savings remains the absolute safest and lowest-cost option. When you pay cash, you don't have to worry about interest rates, monthly payments, or credit inquiries. You walk away with the ring, and your future monthly income remains entirely yours.
If you plan to propose in 6 to 12 months, consider moving your ring savings into a High-Yield Savings Account (HYSA). This keeps your money safe while allowing it to earn competitive interest in the meantime.
Another highly effective way to avoid debt is to look at modern, cost-saving diamond alternatives. Over the last few years, lab-grown diamonds have revolutionized the jewelry industry. Chemically, physically, and optically identical to natural diamonds, lab-grown diamonds cost a fraction of the price. This means you can get a significantly larger, higher-quality stone for the exact same budget—often allowing you to pay in cash rather than taking out a loan.
To explore these options, read our guides on Affordable Lab Diamonds and discover how they offer Lab Grown Diamond Engagement Rings Ethical Elegance for Your Big Day.
How to Choose and Design Your Ring Wisely
One of the best ways to keep your costs down—and ensure you don't need to over-finance—is to skip the traditional retail store entirely and work directly with a custom designer.
At Washington Diamond, our private, appointment-only studio in Northern Virginia allows us to work one-on-one with you without the massive overhead costs of a traditional retail showroom. This means we can source diamonds directly and design a custom ring that fits your exact budget.
When you design a ring from scratch, you have complete control over where your money goes. For example, we can help you choose a diamond that is "eye-clean" (meaning it has tiny natural inclusions that are invisible to the naked eye but save you thousands of dollars) or select a setting that makes a modest diamond look significantly larger.
To learn more about how the custom design process works, check out our Custom Design Engagement Ring Guide as well as our Custom Engagement Rings Ultimate Guide.
Frequently Asked Questions about Engagement Ring Financing
What credit score do I need to qualify for engagement ring financing?
To qualify for the best financing terms—such as a 0% introductory APR credit card or a low-interest personal loan (under 10%)—you generally need a "good" to "excellent" credit score, typically 690 or higher.
If your credit score is in the "fair" range (630 to 689), you may still qualify for personal loans or store credit cards, but your interest rates will likely be much higher. If your credit score is below 630, standard financing can become very expensive, and you may want to consider saving up to pay in cash or choosing a highly affordable lab-grown diamond to keep the purchase price within your immediate reach.
Does financing an engagement ring hurt my credit score?
Applying for any financing option—whether it's a personal loan, a credit card, or store financing—will trigger a "hard inquiry" on your credit report, which can temporarily drop your credit score by a few points.
Once you secure the financing, carrying a large balance on a credit card can also lower your score by increasing your "credit utilization ratio" (the amount of debt you owe compared to your total credit limit). However, as long as you make all of your monthly payments on time and pay down the balance, financing can actually help build your credit score over the long term by demonstrating a history of responsible repayment.
Is jewelry store financing a good option, and what should I watch out for?
Jewelry store financing can be a great option if the jeweler offers a true 0% APR promotional period and you are 100% confident you can pay off the entire balance before that period ends.
However, you must watch out for deferred-interest clauses. Many store credit cards advertise "no interest if paid in full within 12 months." If you fail to pay off the entire balance by the end of the 12th month, the credit card company will charge you interest on the original purchase amount backdated to the purchase date. Always read the fine print carefully before signing up for store-branded credit.
Conclusion
At Washington Diamond, we believe that buying an engagement ring should be an exciting, joyful milestone—not a source of financial anxiety. Our private, appointment-only studio in Northern Virginia is designed to give you our undivided attention, helping you navigate both the design process and your budget in a comfortable, pressure-free environment. To learn more about why we choose to work this way, read Your Experience Matters Why We Work By Appointment Only.
Whether you choose to pay with savings, secure a low-interest personal loan, or take advantage of a 0% APR credit card, we are here to help you get the absolute best value for your hard-earned money. Once you have your budget and financing sorted out, you can begin planning the big moment with The Essential Guide for a Perfect Proposal.
Ready to find or design the perfect ring? Read our comprehensive Diamond Ring Complete Guide 2026 to learn everything you need to know about diamond cuts, settings, and smart buying strategies, or schedule your private consultation with us today.
Have a question about your jewelry?
We've been helping clients with diamonds, custom design, repairs, appraisals, and more since 1969. Book a private appointment at our Falls Church studio.
Book an AppointmentTrusted since 1969 · Falls Church, VA · 703-536-3600
From the blog
View all


